Newsletter3 min read
Another Interest Rate Increase
The RBA has raised the cash rate again - what it means if you're saving, if you're borrowing, and how it fits into a tougher year for Australian investors.

Ashley
Principal Adviser, CFP®
Hi Everyone,
Firstly, I apologise for the recent lack of newsletters (though I'm conscious I was clogging your inboxes after the May Federal Budget), since May I've had a few extra constraints on my time. On the personal side, my partner and I sold our first home and bought our new home, which took up a lot of time (I was home alone for the sales campaign, so I got pretty good at cleaning an entire, fortunately small, home). On the professional side, I'm making some changes to the background structure of my business (there will be very little change for clients, other than updating my email address). I'll provide more detail soon.
Interest Rate Increase
Yesterday the Reserve Bank of Australia (RBA) increased the official cash rate by 0.25%, up from 4.35% to 4.60% (notably, other global reserve banks have recently increased rates, including the US Federal Reserve, the RBA equivalent there, last week). This was the fourth time in 2026 the RBA has increased rates, taking us to the highest interest rate level since 2011.
For those without debt, this is good news. You should get more interest payments on your cash savings. Please check what interest your savings account is receiving, CBA alone has around $100 billion in cash accounts paying near-0% interest!
For those with debt, expect your lender to increase your mortgage rate by 0.25%, they'll email you soon (happily, my lender was the first to pass on the full rate increase). This will increase your monthly repayment.
What should borrowers do?
If you haven't reviewed your mortgage rate in the last 12 months, this is almost essential at this stage. At minimum, see what your current lender is offering to new clients, and call and ask them for that. However, I would strongly suggest speaking to your Mortgage Broker, as they'll be across the best deals in the market and can help you refinance if that's appropriate. If you don't have a Mortgage Broker please let me know, I'm happy to provide referrals.
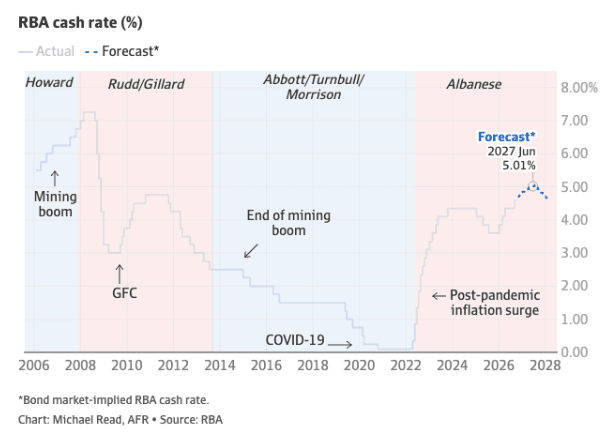
Unfortunately, market forecasts suggest there will be further increases to come, possibly at the next RBA meeting in early November. The table below shows current market pricing for a cash rate of 5.01%, suggesting at least one more increase to 4.85%, and uncertainty of if we get another to push to 5.10%. What happens next will depend completely on the inflation data between now and then, most importantly the quarterly data from July-September (which comes out late October). Nothing is guaranteed at this stage, though Westpac (among others) this morning described a further November hike as their most likely case.
Interest rate increases have only added to a fairly downtrodden 12 months for Australian investors.
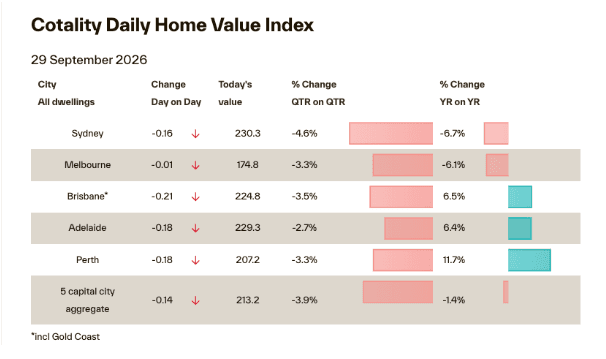
Since I last wrote in May, the Federal Government have legislated their changes to capital gains tax and removing negative gearing (for new purchases of existing properties for investment purposes, new builds and properties already owned maintain negative gearing benefits). These changes, and the impact of the three previous interest rate increases from the RBA, have put significant downward pressure on national property prices, which you can see below. All capital cities are currently losing value, however it's important to note this is a very high level snapshot, and actual property price changes can come down to individual suburbs and price levels.
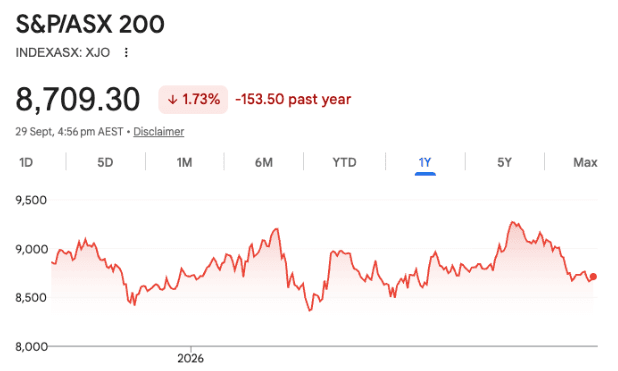
While not directly related to tax changes or interest rate increases, the Australian share market has also been struggling for 12 months now (the ASX 200, the 200 largest listed companies in Australia, is down 1.73% for this period, excluding dividends, see below).
So unfortunately for investors, our Australian assets are struggling, which is dragging down performance. However, while a lot may not feel positive right now, we've had a few good years up to 2026, and our International assets are doing better. I'll ensure I'm more communicative moving forward, but please remember to reach out at any time if you just want to chat.
If you would like to discuss how this may impact you, your family or friends, please don't hesitate to reach out or pass my details on.
Want to talk through how this affects you?
Book an obligation-free 15 minute introductory call.
Book an Initial CallGet the next newsletter
New editions are sent by email when they're published.
Subscribe to the newsletter